… A little bit better than market return with low risk. Interesting for people that want peace of mind. The next one is Birkshshire. Our favorite Birkshshire market cap 1 almost 1 trillion. I got a lot of hate for this in a recent analysis. I said when compared to other opportunities, Berkshire is now a sell because when you look at the net income of 45 billion, the likely growth of 6% going ahead and an average still positive P ratio of 17, then if they make 80 billion in 10 years in profits times 17, the market cap will be 1.3 trillion. Not …
I said when compared to other opportunities, Berkshire is now a sell
Contexto extraído por IA
Birkshshire. Our favorite Birkshshire market cap 1 almost 1 trillion. I got a lot of hate for this in a recent analysis. I said when compared to other opportunities, Berkshire is now a sell because when you look at the net income of 45 billion, the likely growth of 6% going ahead and an average still positive P ratio of 17, then if they make 80 billion in 10 years in profits times 17, the market cap will be 1.3 trillion. Not far from where it is now.
Transcrição Completa
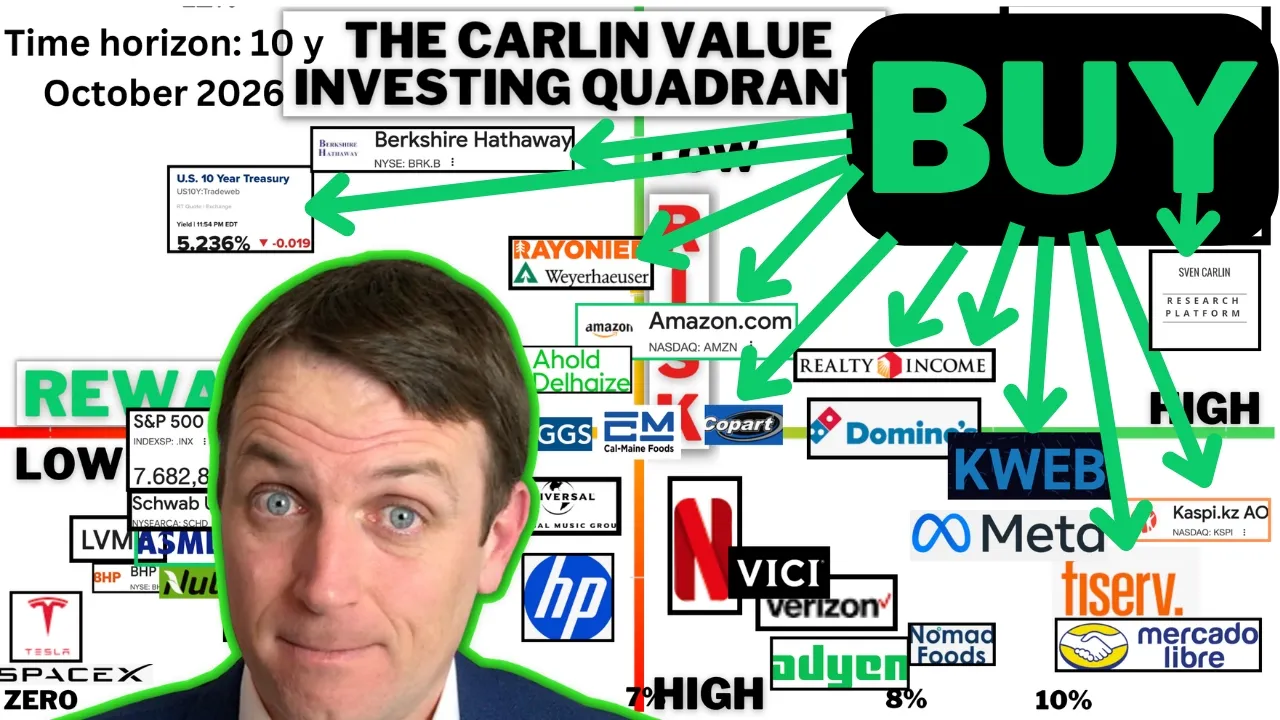
Good day fellow investors. Welcome to the October value investing risk and reward quadrant update. For the new investors here, what is the quadrant? Well, I have created a visual to understand the risk and reward of investing. We have the reward on the xaxis from low to high and risk on the y from high to low. So that from a value investing perspective we are looking for lowrisk highreward investments that should be then here on the higher end of the quadrant and the cell on the lower left end for those who don't know me my name is Carlen have been investing for more than 25 years now did pretty well on my model portfolio did from a value investing perspective equal to the market 15% per year over the last eight years and we focus on risk first fundamentals owners earnings which is something that will trickle down through this whole discussion. For those interested in what I do for my research platform, check it now because at the end of the year the price is going up and if you check it now you lock in the price forever. Now the quadrant got a little bit messy earlier. We are going to completely refurbish it a little bit. I changed put a little bit more space in the returns here. It was up to 12 to create more clarity there. Let's start immediately with now the S&P 500 that I have put here after calculating the intrinsic value on Friday to show the market risk. Let's take the medium here as the market risk. Therefore, the S&P 500 that I think is pretty expensive now and will likely lead to a low return 3 4% at best over time. More on that in the video. All the videos we mention and the companies will have its specific research analysis down below in the comments. So, let's now start from the riskier side of things. Tesla, SpaceX, and with Tesla, with SpaceX from a value investing perspective, this is all blah blah miracles, promises, no tangible profits from the cars, from this, from that. So, it's unsustainable. It will likely end someday. Therefore, not to invest. And that's why we have them here at a zero return. Next company, ASML. Another AI machine production company. And it has done really well over the last year and a half, more than two times up. The P ratio is now 60. It was in the 20s. And this also shows how the quadrant works. If you look at this from March 2025, look, ASML a little bit higher risk but offering a 12% return among other companies. Samsung, we'll discuss, ADM, Nutrian, all were there priced at goodbyes. Now they are priced at goodbye companies because the price went up but the company is still the same. If we discuss the outlook a little bit improved on the positive side of their long-term outlook when I make the calculation 60 billion in revenues reached by 2030 60 something profitability net profit margin 30% that's 20 billion and to justify the current market capitalization of 610 billion when they reach 20 billion they need to double again the net profit and then double again to give you a good return. So what's priced in is doubling doubling for the next 15 20 years and that's a little bit too risky a little bit too crazy to pay a P ratio of 60. Further something that helps me a lot is my intrinsic value table just as an overview of the investment opportunities the expensiveness the cheapness of those and there we also have ASML. You can download this for free in the link in description below on my free course. And we have here scenarios that we'll discuss for most of the companies throughout the overview. Earnings per share. How much do they need to grow to justify the current stock price? Where does the P ratio need to be? They need to keep on growing at 15% per year. And the P ratio needs to be at 40, which is a little bit high. Let's make it 25. And then you see that it is too expensive now at 1,600 compared to the intrinsic value exuberant times 20% growth every year for the next 10. Okay, P ratio down the road of 30 present value. Okay, that is priced in slower growth rate still a good P ratio where we were a year ago. And this is not linear. This is not predictive. This is okay. This is something interesting. If the market gets negative, this is where I might look at a company. This is where I might get the margin of safety. And then this explains what's priced in now. And this let's say an average summar is too expensive likely to lead to a low return long term. That's why I have put it here. a little bit riskier than the market as a whole because it's full of AI yes mode and everything but everyone is going after them. So pushed it a little bit higher on the risk side that's lower risk because I am changing the risk as market risk. The next one is Schwab. Now, it is down a little bit as interest rates went up, but I'm surprised that it went up so much over the last year despite rising interest rates. We go back to our intrinsic template. The dividend is there. If it grows at 5%, if you expect a 5% dividend yield down the road, thus declining from the current 3%, then intrinsic value is much lower than the current stock price. higher growth rate 7% everybody happy down the road all the time with a dividend of 3% 100 divided by 30 3.3% then the current present value is justified for a 10% expected return margin of safety 3% growth recession 67% expected yield which can happen with higher interest rates the margin of safety there is much lower 3% % simply too risky especially if I look at the companies there when we'll discuss Verizon but these are marketpriced companies so from this perspective I'll put Schwab here as likely like market returns at market risk next one is Archer Daniel Midland the food company another insight into the past of the quadrant again March 2025 here it was as a strong buy, high return, 10% low risk. And what happened since then? Well, the stock is up significantly. The dividend is not close to 5% anymore. It's two. And that changes the whole game there. So, I'm also putting Archer Daniel Midlands here in marketlike returns, marketlike risks, perhaps a little bit better, but I need it cheaper. The next company is McDonald's. We discussed it in a recent video. Made the calculation nothing spectacular. So again, one to put it with the market risk basket there. Similarly, Pepsi, we made the intrinsic value calculation. Depending on how exuberant you are, but given the competition, the brands, the I don't see crazy growth ahead, present value, something like Nike pretty much lower. Given the risk and reward, I'll again put it with the market returns there. And that holds for nutrient, BHP, Starbucks, LVMH that we all discussed links in the videos below for the details. We are putting it here in the let's say marketlike basket. Now we have to discuss the 10-year Treasury that was 4.7% just a month and something ago. Now it's already 5.2%. So that is changing. Interest rates are going up and the risk-free rate of 5.2% is starting to get interested. Yesterday, we discussed specifically bonds with our $1 million portfolio allocation series that you have to see how it fits you. If rates go lower, you can even profit on these long-term bonds. From that perspective, I think it's lower risk than market 5.2% 2% return safety. Therefore, I would put it here. A little bit better than market return with low risk. Interesting for people that want peace of mind. The next one is Birkshshire. Our favorite Birkshshire market cap 1 almost 1 trillion. I got a lot of hate for this in a recent analysis. I said when compared to other opportunities, Berkshire is now a sell because when you look at the net income of 45 billion, the likely growth of 6% going ahead and an average still positive P ratio of 17, then if they make 80 billion in 10 years in profits times 17, the market cap will be 1.3 trillion. Not far from where it is now. Therefore, I said it is risky and not a buy. However, we can be sure that Birkshire will deliver perhaps something more, perhaps something less. Let's say that they will keep on growing at 6% low-risk fortress balance sheet. So, a little bit better than treasuries, but not far from there. Very low risk, all equal improving Berkshire here. Ryioneer, this is now getting interesting. The lumber, timber, the stocks are falling like timber. We discussed this in an interesting video. And when it comes to these companies, warehouse are also going down. Dividend they are likely to be paying the 4%. The trees keep on growing. So that is something to think about. And then they also expect more growth in IBITA. If they hit that they have some debt. Okay, that's normal for REITs. Stock is down because they have lowered their Q free estimations because of lower lumber pricing housing. But if housing reverts, you're getting a dividend and significant upside when and if housing reverts, this can easily double. If they hit their 1.5 billion of EIA, 1 billion of cash flows, plus the trees are growing, the businesses are growing. This might be a low risk. The return is not yet 10%. I would like to see it here, but we are at 6 7% likely long term. and you're owning trees. Perhaps we need to separate warehouser, but that will be for another date with Ryioneer as the companies are a little bit different. We continue the elevator companies that we discussed, high competition was my key issue. Okay, I'm going to put them into the market basket. Greg's sausage rolls in the UK. The stock has recovered a little bit. Still a good dividend. Still some growth there. Let's put it at 7% marketlike risk returns. Verizon 6% yield, but the company is burdened with a lot of debt. So some growth there. Okay. But I'm going to put it here at a high risk. Let's say 7 to 8% return. Eggs, calm foods, we discussed this in a general video. And with X prices lower, the stock has finally reacted. I was a little bit surprised here that the stock is not reacting yet. Now it started reacting. If we look at the numbers, uses of capital in an average year 300 million to give back to the companies. They did some buybacks. Okay. But let's say things stabilize to normal times. Maybe they are now at 200 million. I would need this to be at two billion. It's not far from where it was just a while ago. So, we are keeping an eye on it and watching these egg companies putting it here at 7%. Now, when it comes to 10% and lower risk, it might be interesting. That's why we are watching this. We just discussed the Las Vegas REIT property 7% yield likely protection. The market is concerned about the holders there, the big two tenants changing hands, not changing hands, but we have a 7% yield. Perhaps a little bit riskier than the market, but the yield is there. We discussed recently Universal Music Group. Some say it is a mode. Billman says 5x stock price target, but let's put it here at 7% now, which would be the absolute, not the relative return from there. Next one, Microsoft. Let's go to the calculation. If I take the earnings, the growth rates, I put it 15 10% P ratio of 20. Yes, we are close to the current stock price. If they grow even faster on a higher multiple, okay, but I don't believe the growth there is sustainable. It's all engineering AI. So for me, Microsoft is very low intrinsic value. I've decided to put it back to where it was here at the market basket. Let's say risk situation. Amazon for me is still Amazon. And if we find it here on our intrinsic value table, if I make the calculation, if it grows 20 and 15% going forward with height P ratio, it's still cheap. On a fair value, this should be a fair value. Five, six, 7% return likely going forward, but a little bit expensive now. But that 7% given the quality of the business I have to put it as less than market risk and better return. We'll discuss this. I'm looking forward to your comments. HPQ we discussed it here when it was as a buy on the quadrant. Now the stock is almost a double. I have to bring its 3% dividend buybacks. I have to put it somewhere here. now as more risky if the market sentiment turns. Netflix the stock is down but when it comes to the company it will depend on the growth rate going forward. Is it now a mature company that can grow double digit for the next years and still with a high P ratio is still overvalued even higher what is expected by the market now if the growth slowdowns riskier so I'm going to put it at 7% but more risk another growth company aden not doing great if I calculate the growth rate to be at 20% for the next five years with declining growth puts now it is a little bit questionable let's go to this it is still a bit risky so I'm transferring it to yes good returns possible but higher risk next one is ah hold the US European retailer down a little bit dividend 3% they are doing buybacks that should grow the dividend if you expect 4% dividend yields you need it in the high 20s if you want a margin of safety, you need it in the low 20s for a 10% return. Now, what's priced in is 6% growth forever in the dividend. Expect a dividend of 3%. A little bit too much. So, I'm putting it here. Dividend buybacks 6 7% stable returns, but keep in mind the long-term risk of the stock. We just discussed realy income. The return looks like 10% going forward. I would even say less than market risk. So let's put it here as something interesting. Copart a lot of discussions there. I made the valuation analysis and we are depending on how you look, how exuberant you are, but we are still a little bit far from a fair valuation there. So I'm just bringing it 7% likely return 78 marketlike risk. Nomad Foods traded on the NASDAQ good dividend buybacks. It did recover a little bit. Now it's giving it back high risk because of the debt but high potential for good returns. Let's say dividend buybacks 8% going forward. But given the that I think I might transfer it to the bets quadrant that we'll discuss next week. Domino's Pizza UK dividend some likely growth inflation protection 78% likely long-term return dividend inflation protection. That's okay. Then we have meta. And if we go to the calculation if we put just 8% growth and the P ratio there and the dividend payout. Okay, we are not far from the stock price. Just a little bit further growth and people are still crazy about Facebook, Instagram, then we are even cheap. Crazy situation but okay it is there. So I have to put it here as perhaps a little bit riskier than the market but way better return getting into 10%. I might not like Mark but it is what it is from that price perspective. We just discussed the Chinese companies high cash flows all anything very bad sentiment when it comes back it should give a positive return 10% likely return there as it rebounds marketlike risk very interesting perhaps even a little bit less than marketlike risk but it is China let's keep it at marketlike risks ferve it is a 2027 2028 reversal just a little bit of growth on clover. The other stabilizing P ratio 15 you are at 90. So higher risk than market a little bit but good return. Marcado Libra growth stock they are beating my growth estimations fair and square and even with these conservative numbers the value intrinsic value is there. So I'm keeping it here at plus 10% return at higher risk. Kaspi just discussed perhaps high yield, high growth, everything. Something to consider for that value pillar of your portfolio. I'm also considering it. So this would be the updated quadrant. I think it's much clearer than before. I'll discuss the bets separately. Put nomad foods in the bets too. So, I own two companies of the Chinese internet stocks in the diversified portfolio. Contemplating still Caspie for my diversified portfolio. Don't forget you can check whatever I own. 21-day money back guarantee on my research platform. Check it in the link in description below or this video in the description. The price is going up next year. You can lock this price forever if it is valuable for
Comentários 0
Entre para participar da discussão.
EntrarAinda não há comentários. Seja o primeiro a compartilhar sua opinião!