…erating profit instead, because that's the profit that Amazon actually earned. My system, trying to keep me honest, has Amazon at fairly valued because Amazon did go from making cash to burning it while it builds all of those data centers. But this is where I go against my own system, where I see Amazon as still a buy because the money is going into the part of the business that's speeding up and getting more profitable all at the same time. Nobody had a bad word to say about this next company in the group, and it barely fell at all, which means there probably isn't much of a sale for you to buy into. That's Microsoft, and a Drinomics actually sold it because the price had alr…
But this is where I go against my own system, where I see Amazon as still a buy because the money is going into the part of the business that's speeding up and getting more profitable all at the same time.
AI-extracted context
My system, trying to keep me honest, has Amazon at fairly valued because Amazon did go from making cash to burning it while it builds all of those data centers. But this is where I go against my own system, where I see Amazon as still a buy because the money is going into the part of the business that's speeding up and getting more profitable all at the same time. Nobody had a bad word to say about this next company in the group, and it barely fell at all, which means there probably isn't much of a sale for you to buy into.
Full Transcript
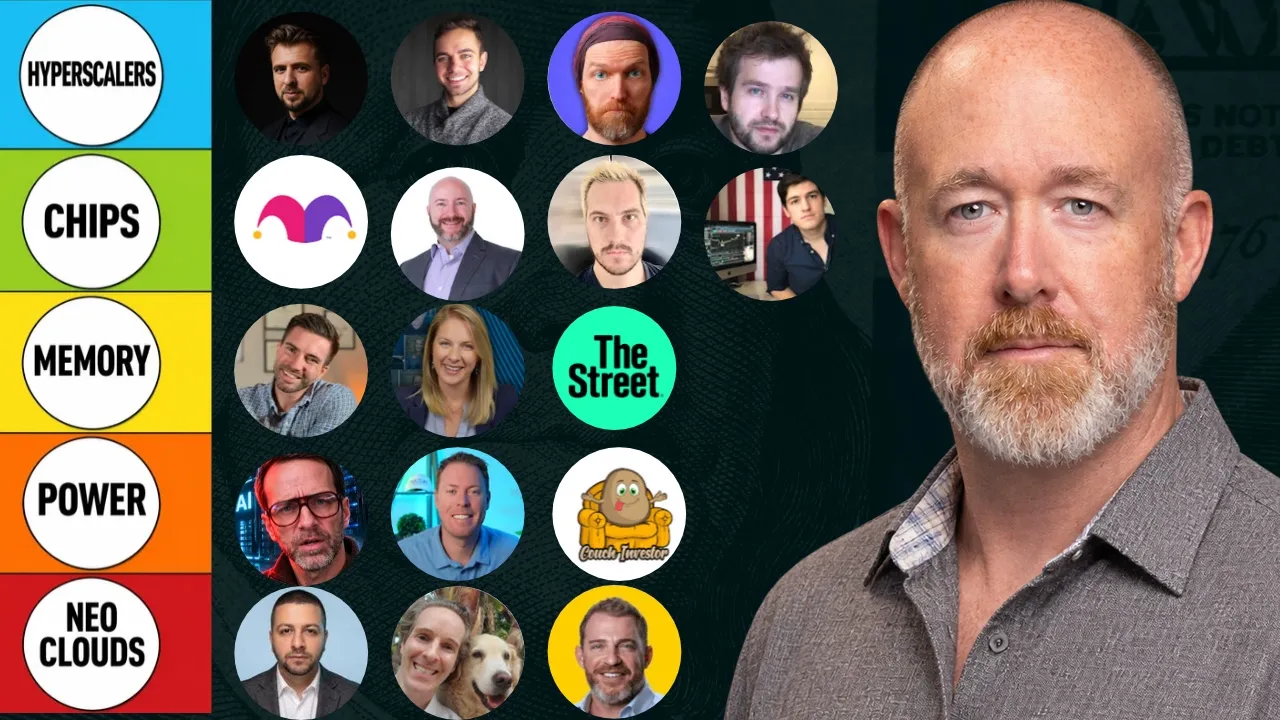
A portion of this video has been sponsored by Goldhaven Resources. Nasdaq down by five and a quarter percent. >> And we have some significant breaking news just in over the wires. Jensen Huang has resigned as president and CEO of Nvidia. >> The market showed real signs of a correction and I get it. The thumbnails, the news articles, everything is screaming crash. But there are a lot of great investors who see the opportunity in a pullback like this. >> This stuff happened 25 times over the past 15 years. It's very common and it's very normal contrary to all this bull you're hearing from people who are trying to clickbait you into emotional decisions. >> I went through the videos of 16 YouTubers who are bullish on this dip and rather than you having to watch every single one of them, I'm going to give you the cliff notes on the companies that they agree on and then how I rank them. I'm also going to be throwing mine in the mix too because I did talk about this last weekend right after it happened. The crowd's favorite started with the companies writing the checks for all those AI chips and they liked them for very different reasons. >> Wall Street sees that as a negative, which is ironic because if these companies decide to spend more on CAPEX, they say that's bad. They're spending too much, but if they start cutting back, they're going to say sell everything. The AI trade is done, which in other words means there's no way to win this. >> The first one makes almost all of its money from ads and every channel that talked about it last week was bullish. That's eight out of the 16 channels and not one of them was bearish. The other eight, well, they just didn't talk about it last week, which doesn't mean they aren't bullish too. And the bear case on it all year has been that it's spending way too much money on AI and the Motley Fool flipped that around. >> And and now we're back to being to me very undervalued and that's Meta, but they see ad impressions go up. They they they still manage to find more users for their family of apps. >> That's Meta and the numbers back that up. Last quarter, Meta grew its sales about 26% with about 15% fewer employees than a year ago while getting paid more for every ad that shows. The obvious catch is the spending. So last quarter, Meta poured so much into data centers that essentially burned up all its cash after making plenty of it a year earlier. Even then, my system says that Meta is trading at a discount right now. Even my price ladder has it sitting as undervalued. And when the business and the price line up like this, well, it happens to get my attention. For this next company, almost every channel was bullish on it, and most of them pointed to the very same thing, which is its cloud business. Nine of our 16 YouTubers were bullish on that last week, and only one channel was bearish, and I'll get to him in just a minute. >> Microsoft's Azure continued expanding rapidly, and AWS, it just reported its fastest growth that we've seen in nearly five years. Does that sound like a demand issue? Not in the slightest. >> What matters with Amazon is the trend in that cloud business. So a year and a half ago, AWS was growing at about 17 %, but it's sped up every single quarter since then, and now it's close to 40 %. AWS profit is growing even faster than its sales, where it now makes up about 63 % of Amazon's entire operating profit, up from about 53 % a year ago. Sasha happened to be the lone bear, and I think his point is actually worth hearing. >> Well, those earnings are one-offs. 46 % of Amazon's profit comes from revaluing their investment in Anthropic. >> Amazon does own a big stake in Anthropic, and it gets counted as profit every time that Anthropic's value goes up, even though it has never sold a share. You can see it in the forecasts. Analysts actually expect Amazon's earnings per share to go down next year, which tells you how much of its year's profit came from those kind of paper gains. That's why I watch AWS's operating profit instead, because that's the profit that Amazon actually earned. My system, trying to keep me honest, has Amazon at fairly valued because Amazon did go from making cash to burning it while it builds all of those data centers. But this is where I go against my own system, where I see Amazon as still a buy because the money is going into the part of the business that's speeding up and getting more profitable all at the same time. Nobody had a bad word to say about this next company in the group, and it barely fell at all, which means there probably isn't much of a sale for you to buy into. That's Microsoft, and a Drinomics actually sold it because the price had already caught up to the business, not because the business went bad or anything like that. And for Microsoft, eight channels were bullish on it last week and not a single one was bearish. >> I don't think Microsoft is expensive. I find it more or less fairly value compared to the rest of the market. >> The thing that I would point to is the bookings. A year ago, Microsoft had signed contracts covering a little over a year of its sales, and now that's about two full years on a much bigger business. On Microsoft, I'm a little closer to a Drinomics than for the rest of the bulls. The business is about as strong as it gets, but the problem is the price. Its PE is at about a 27, which is right around its tenure average of 29. So there's really not much of a discount, and I'd be paying full price. Microsoft is a solid choice to own, but right now I just don't see it as one that I want to chase along with everybody else. Every AI and growth company runs on chips, and building those chips requires a lot of high demand resources, where right now the US is racing against China to secure possession of critical metals, which brings us to our paid advertisement disseminated on behalf of Goldhaven Resources Corp, a Canadian exploration company going after silver and tungsten on its 37,000 hectare Magno project in northern British Columbia, where tungsten, the hardest metal in nature with the highest melting point, happens to be one of those high demand metals. It is indispensable in semiconductor manufacturing, military equipment, aerospace parts like those in the F-35s. And China produced about 80% of the world's mined tungsten just last year. The US has zero operational tungsten mines, and Canada doesn't have a producing tungsten mine either. And that is a real choke point where Wall Street is obviously paying attention because in October, CME Group said it plans to launch tungsten futures in early 2027 once regulators sign off. So CME puts the global tungsten market at over 20 billion dollars. Now both metals have pulled back hard this year where silver is down about negative 57% from its January high and tungsten has about negative 68% since March. Silver is likely been trading down on the US Iran headlines and higher rates and China hosts the Apex Summit November 18th. With the US China trade truce set to expire January 10th, nobody knows how either one plays out, but if those stories flip, these two bear markets could flip with them. That's what makes Magno worth knowing about. It holds tungsten and silver lead zinc zones on one property and Goldhaven drilled its first holes there back in August starting at the historic Kun tungsten zone. Now it is in its early stage exploration and not a mine. So it has metals that the world can't do without trading well off of their highs. So that's the opportunity setup. As always, do your own due diligence and check the link down in the description to learn more about Goldhaven Resources. Nvidia and AMD are where myself and the rest of the YouTubers pretty much overlap the most because both were on my list last week. Since that mini little crash on November 5th though, they've gone in complete opposite directions. Nvidia never really got off the mat and AMD bounced really hard. Nvidia was one of the most talked about companies in this whole group. Almost every channel that covered it was bullish and only one said wait. No surprise that eight of the YouTubers were bullish and I'm going to get to one of them that said wait in just a minute. Almost every one of them made the same point which was the price. Nvidia's PE is running at less than half of its usual level and it almost never gets that low. That's not because the business is fading either. So a year ago, Nvidia's growth had slowed to about 56% and last quarter it sped back up to over 100%. The bulls weren't ignoring the risks though. They kept coming back to the same one which was Jensen Huang himself. >> For I do think that this situation with Nvidia and Jensen is a little bit because it's not simply the CEO having an affair, it's that Jensen is the face of NVIDIA. And the company doesn't really have a guaranteed succession plan. >> Park Kev even put a number on that worst case using an estimate from Dan Ives. >> Oh, NVIDIA is worth a lot less and he noted 25 to 30% as the range is not that much of a reason for NVIDIA stock investors to panic and sell. >> Then on Thursday of last week, the worst case actually happened. Jensen had already admitted to one affair and then he resigned as CEO when a second one came out with an NVIDIA executive who reported directly to him. The CFO Colette Kress is running the company until the board finds a permanent CEO and without surprise, the stock got absolutely hammered with that type of news. >> They honey potted Jensen and I just put 35 grand into his stock to take advantage of this sell off. >> And the one channel that said weight was the street. Their guest advice was to stay away from NVIDIA until the questions about its CEO got answered. He also said something that every NVIDIA owner needs to hear. >> Sometimes people confuse conviction with position size. Just because it's grown in such a way and you've left it there, it becomes your highest conviction. But I think if investors reduce their NVIDIA allocation, that's a lot of money that's going to go other places. >> Confusing conviction with a position size is a trap that I watch for in my own portfolio. NVIDIA is already a big slice of my portfolio and it grew into that slice all on its own. My own price ladder says reassess on NVIDIA because it's fallen so much further than it deserves while the business is still cranking. We're all going to find out together in the quarterly earnings report this week, which happens to be NVIDIA's first without Jensen. For me, I'm not doing anything different. I'm holding because I don't have any more dry powder to use, but if you don't own NVIDIA and you've been waiting for a really good dip, this happens to be a pretty fantastic opportunity. AMD happens to be the other story and nobody was bearish on it. Interesting enough, seven channels covered AMD last week, and all seven were bullish, me included. It reported another great quarter, and then it fell about 17% in that sell-off anyway. If you're wondering why I can't sell AMD stock, I mean, that's a huge part of the reason. If I can run a bear case on a stock and still get a scenario where that stock's going to probably outperform the S&P 500, that's that's pretty darn intriguing. >> Analysts now expect AMD's earnings per share to more than double next year, and they've raised that estimate by about 15% in just 3 months. >> But Nvidia 0.4 AMD relatively expensive. That's because it's not growing quite as fast. Its earnings, its profitability isn't quite as good as Nvidia. >> AMD is still one of my anchors, and I did happen to buy more on November 5th when it dropped. But after the bounce, it's more expensive than it's been almost any time in its own history. So I'm not adding anything extra, and I'm just sticking to my regular schedule of dollar cost averaging. The worst single drop in the entire S&P 500 on that November 5th came from a company that makes storage for AI data centers that they rely on day in and day out. And that was SanDisk, down about 22%. And then Micron, which makes the memory AI chips need to do their work, fell about 17% the very same day. Now, the bears say that memory has always been a boom and bust business, and that's the whole fight over Micron and SanDisk. Among the channels that I watched though, nobody was bearish on either one. Nine were bullish on Micron, and four of those were bullish on SanDisk too. But as of right now, it's a boom unlike anything that I've seen in this industry. So Micron now keeps about 81% of its sales as operating profit. But if you look back at just even a year ago, that was only about 33%. >> The market is kind of disconnected viewing Micron through its legacy lens versus through its future lens and through that demand for HBM memory. Um, AI and inference is really not going away. It's it's entrenched. It's going to be growing over time, and that supports a a long runway for growth and for solid earnings for Micron. >> The argument is that Micron's newest AI memory gets replaced with every new generation of chip. So buyers have to keep coming back every year. Now my system, which is mathematically based, flags both of them as being at peak earnings because record profits are usually what the top of the cycle looks like, at least historically. But from my point of view, I don't really think this is the same old cycle anymore. If it's still a cycle, it's been stretched way out because the demand runs so far ahead and so much of it has already been booked. Now the most important thing that I didn't really hear anyone mention is that SanDisk has a reservation book too. It has about $89 billion of business signed that it still has to deliver, which is more than two years of sales already under contract. Like I said, those are signed orders and they're a lot harder to just walk away from than just a one-off sale. Memory still gets a smaller slice for me. That's not because I think the bust is coming, it's because these stocks swing much harder than the rest and they just proved it with a negative 22% day. The next company sits on the power side of AI. So data centers need a lot of electricity and the grid can't keep up. So the company builds fuel cells that make power right on site. That's Bloom Energy and only a handful of channels actually covered it and all of them liked it. And that handful was just four YouTube channels. But even the bulls, like at Dumb Money, admit there's a little bit of a catch. >> And I'm long Bloom too, but I think the the thing to worry about there is is not the demand. They they have plenty of demand. It's their valuation is so high and they have uh negative cash flow. >> That worry in that clip is fair for last quarter because Bloom's cash flow was negative. But what got lost in all of this though is how far Bloom has already come. So about six years ago, Bloom's operating margin was about negative 20%. So it was losing money on all of its sales. And over the last year, that margin was about 15% and it brought in more cash than it actually The growth is speeding up too, and Bloom's sales more than doubled from a year ago. And of course, analysts have noticed, and they've been raising their earnings estimates without a single cut. The PE on Bloom looks pretty scary, and that's the bear's whole point. Once you adjust it for how fast Bloom is growing though, it's near the cheapest that it's been all year. Once again, my system is a bit cautious on Bloom because last quarter the cash didn't keep up with the profits. So for me, I'd size Bloom pretty small, the way that you'd size any company that's still trying to prove itself. Up to this point, the crowd of YouTubers has pretty much agreed with each other. But the Neo Clouds are where they're going to completely split, and those are the companies that ran out AI computing power like Core Weave and Nebius. Now with Core Weave, more of the channels that I watched were bearish than bullish, and most of them made that call before Core Weave reported on November 10th. On Core Weave, six were bearish and only three were bullish. Nebius split them pretty much as well with three bulls against two bears. The obvious bear case just came down to one word, which is death. >> Is Core Weave an opportunity or a trap? >> I think it's a trap. I I I just we love strong balance sheet companies, uh dominant market share, but the balance sheet there just is very concerning. >> So when a company's bonds pay 16 %, the lenders are telling you that hey, they're a little bit nervous. Then Core Weave reported, and the bookings told a completely different story. So its backlog of signed future business climbed to about 132 billion, more than double what it was just a year ago, and its sales growth sped back up to about 168 %. Now if you do own Core Weave, the problem is that it's still losing money while it pays about a billion dollars a quarter in interest on all of that debt. Now Nebius, where the channels were also split, reported on November 12th with sales up about 570 % from a year ago. And a big piece of that though was a one-time payment, and it happened to lower its full year target to the bottom of its range because new capacity is late to coming online. The best way that I heard anyone sort out this group really came from MarketBeat. >> These are NeoCloud landlords. They already own the land, they own the power, they own the building, and if a new chip makes last year's GPUs obsolete, it generally tends to be the tenant's problem, not this company's problem. >> Landlord or operator I I think is really the right question to ask. So a landlord with a 15-year lease gets paid no matter which chip is going to win. And a company that buys the chips with borrowed money is is the one holding the bag when those chips are going to go out of date. In my mind, this is the riskiest corner of the whole AI trade. And and my system says new money should wait on all of them because none of them is making really a real profit yet. And that's the obvious reason why this is the tiniest slice of my portfolio and it's never part of my core. So a lot of people feel like they already missed the bottom. Felix Pren had a pretty good answer for that on MarketBeat. >> I actually think it's the smarter point to buy if you have a little bit more of a lower risk profile because you've seen some confirmation that some money is actually flowing back into that. Position sizing allows for it. You know, you can you can nibble on things that just seem a lot better value. >> Me personally, I don't know where the bottom is and and nobody else should really say that they do either. So nibbling is exactly how I approach a market like this one today. It's also why my ranking follows the way that I build my own portfolio. It's heavy with the anchors and it's light with the ones that are going to swing around the hardest. For me, the anchors always come first. So meta leads with the list because the business and the price finally line up. Amazon is next and that's my call over my own system. And then Nvidia comes after that for anyone who doesn't already own it. Microsoft and AMD are great companies to hold and of course I'll be buying when there's further dips, but neither one of them is one that I'm going to chase at today's prices. Then the middle tier is Micron, SanDisk, and Bloom Energy where Micron and SanDisk are strong businesses and is still going to be proving itself, but all three of them swing much harder in both directions. So, for me, they're going to get smaller slices. Then, of course, there's the Neo Clouds that sit at the very bottom, and that happens to be my smallest slice of investment. Honestly, I'm surprised the YouTubers agreed on as much as they did. So, most of the crowd did land on the same side, and the Neo Clouds were really the only big fight. And on the businesses, like for the most part, I think they're mostly right. Hey, I hope you're able to get some value from today's video, and I would really love it if you'd consider pressing the like button and also subscribe if you haven't already. But I do want to point something out. I'm not a financial advisor, and I do this for educational purposes. Outside of that, hey, I hope to see you on the next one.

Comments 0
Sign in to join the discussion.
Sign inNo comments yet. Be the first to share your thoughts!