FIS, GPN, International Paper, IP, SW, PKG, Bunge, BG and more - S&P 500 419 tp 396...
- Rendement de la vidéo
- -4,24%
- Appels
- 1
- Achat / Vente
- 1 0
- Publié
Recommandations
L'entrée est le cours de clôture de l'actif à la date de publication. Le cours actuel est la dernière clôture enregistrée.
-
Entrée $257,75 16 nov 2026Actuel $246,82 20 nov 2026Résultat −$10,93vs. indice +2,5% SPY −6,8% sur la même période
Citer cette recommandation Voir le segment source (134s) *
Contexte de la transcription source
…he S&P 500 that are at the bottom of the S&P 500. There are some bets like Charter Communications where the upside is high but so is the risk. and perhaps focusing on that 6% return that's not far from our estimation of Amazon for example. So you have Amazon or you have Textron offering you jets at the same price. When you compare I would still go for Amazon. We've discussed housing. To conclude on the S&P 500, yes, it is the most expensive market in the world, but if I find just a few companies that I can follow over time, that makes me happy. And now we'll touch on some companies here, but le…
So you have Amazon or you have Textron offering you jets at the same price. When you compare I would still go for Amazon.
Contexte extrait par IA So you have Amazon or you have Textron offering you jets at the same price. When you compare I would still go for Amazon. We've discussed housing.
Transcription Complète
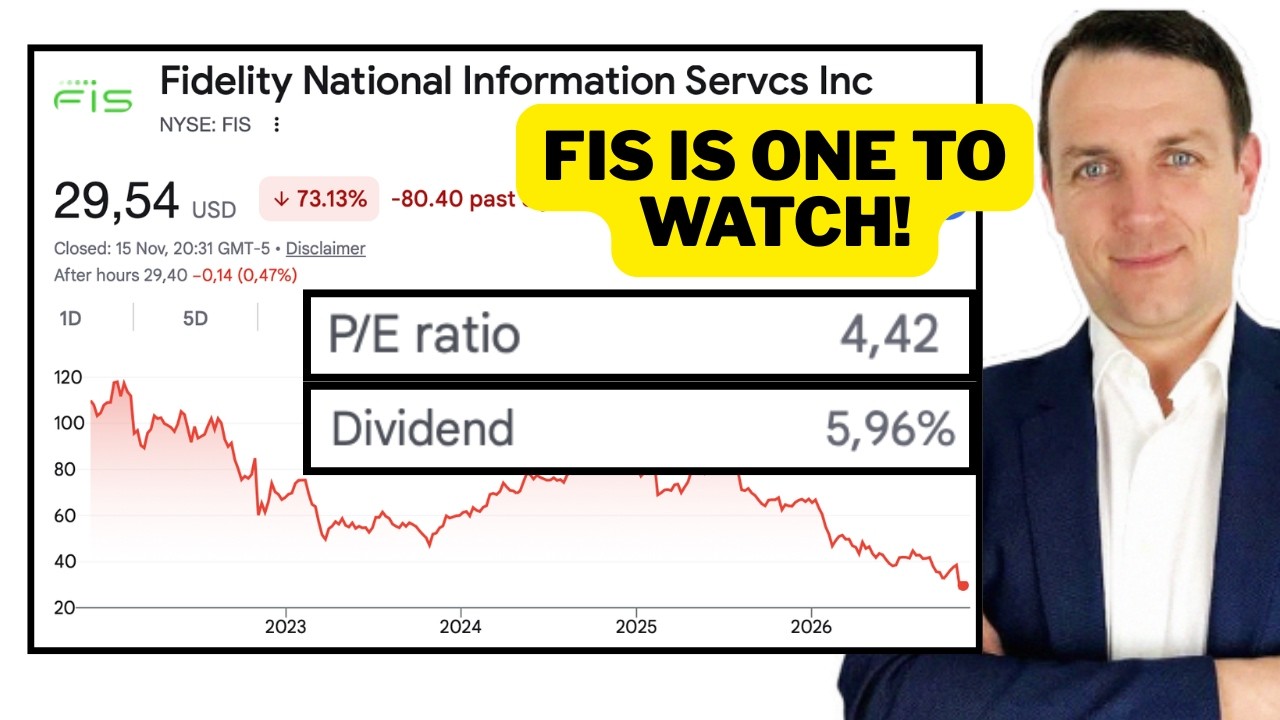
Good day fellow investors. We continue with our stock by stock analysis of the S&P 500. We'll discuss a lot of interesting businesses. But let's start with the conclusion as I have looked at the bottom 100 stocks of the S&P 500 already. And apart from some peculiar stocks here and there, I must say I'm not amused now that I have covered the bottom 100. We have focused on the most interesting things every 20 stocks that are comprehensed in a video. We have had housing lenar it's getting interesting but you have to accept that the negative sentiment for housing is there which makes them cheap. Other companies echo giving you a discount on the value of SpaceX AI situations things like that. the Lulus, the decks that are also in the negative sentiment and only the stocks that are in a very negative situation look affordable or cheap. The rest of the market is relatively priced, which it might not be a surprise for the most expensive market in the world, but there are always surprises. We have made a video on Mosaic. We'll put the direct video in the link in the description below. I bought some as a cyclical strategical purchase for my diversified portfolio. Pentare it was cheap then first earnings good earnings up 30% and now it's already lower than the expected 10% return. You can see the jump here. But most are fairly priced. Domino's Pizza's 6% return shareholder return and 67% is the expected return from investing in these businesses of the S&P 500 that are at the bottom of the S&P 500. There are some bets like Charter Communications where the upside is high but so is the risk. and perhaps focusing on that 6% return that's not far from our estimation of Amazon for example. So you have Amazon or you have Textron offering you jets at the same price. When you compare I would still go for Amazon. We've discussed housing. To conclude on the S&P 500, yes, it is the most expensive market in the world, but if I find just a few companies that I can follow over time, that makes me happy. And now we'll touch on some companies here, but let's start with the one that is most interesting of this batch, and that is also for you that many have requested it, Fidelity National. Now, Fidelity National, the payment processor, 1 billion cards processing 30% of US economy. Everything looks good, but nothing stellar on the revenue side. The business is there. 90 million core banking accounts, 1 billion accounts of file, 52 billion car transactions. So, the business is there. However, the outlook is not great. They have adjusted it lower it especially lowered for next year and therefore the stock continues its decline. There is free cash flow and on that metric the stock looks very cheap. But when they tell you that revenue growth might be negative, margins not expanding flat, hopefully free cash flow flat, then we know the business has some issues. And then if you look at the stock price then the issues multiply because just over the last few years and especially the last year and a half this company has been murdered. So the P ratio is now four the dividend yield is 6% and they aim to keep it. So you wait for improvements while the dividend is 6%. They cut guidance for second consecutive quarter adjusted EPS decline departure of the CFO. Michael Barry also says that they overpaid for global payments network. World pay 13 billion at a double digit IBITA while the company is trading at seven times ITA. So for now it remains the dividend then lowering that and then hopefully improving that will improve the situation. And very interesting that many of you have asked about the company Fizz especially when we discussed Fiserf. How do I look at that company? However, with these companies, you have to accept volatility because when the stock was higher, questions were the same. Two months ago, five months ago, it looked cheap and it continues to look cheap. Anyway, Michael Bur knows a little bit more than me here. I'm just a global value investor trying to look for value where I find it simple and understandable. And why not go with people that have been following the segment for years. World pay acquisition that has traded hands three times in the last six, seven years, thus going lower. And then also compared to the takeover values for somebody that would take over this, they would need a 10% plus free cash flow yield to pay for the debt to take this over. That's why GPN is trading where it is. So Fiser is cheaper compared to the others. Optical cheapness there. Yes, everything looks cheap, but there is something even cheaper. World Pay keeps changing hands. If we look at the metrics there, Fiserf is trading there with others. But we have improving numbers, especially given the last quarter. If they can keep that up, lower leverage starting buybacks. They are just focusing on the dividend. These guys are doing great buybacks. These buybacks are always risky because when you go for these buybacks without knowing that the future will be better, that's always discounted. So all great returns expected going forward. Equity yield. All good. Barry says that Fizzer has a castle. This will be taken over. This is overlevered for the acquisitions they have made recently. This is looking better. We have bought it early when it was bottoming on oversold practically. Now things are stabilizing. If it continues we'll do well. GPN global payments network also looking good. If they can do the buybacks maybe being taken over might be okay. F yield they have to focus on that with the negative guidance. It doesn't look great. Nobody likes it, but on one side it is so incredibly cheap. So why not look at this? Maybe not now, but over the next 12 months. So what have I done? I have added it to our best part of the quadrant here and we'll be following it over time. For now, they're giving negative guidance. If there is more bad news, the market will adjust to that bad news. Some of it is already priced in always some of it. And then as they stabilize, if they show that resilience of some businesses, then there might be upside down the road. So why not follow it? Very interesting, very cheap. Some of you probably already have a position. Let's go immediately to Global Payments Network. The takeover has been paused because of financing issues for those who wanted to take it out and you need 45 billion for this to take it over with the debt and then you look at the cash flows and then those would barely cover the debt and that's why let's say now it is fairly priced on that takeover price. But the numbers look good compared to the price. If they can manage their 18 billion of net debt, okay, bars fair value is between 45 and 60. At 90, it makes no sense for people to take it over. That's why the takeover failed. So these were the most interesting things of this. Let's now go one by one. There are some interesting stories here. Some we have already discussed over time. Let's just go around them. It's always interesting to look at these businesses and just see what's going on in the market. Jacob Solutions clear compounder. When you look at the stock price, everything is growing, especially built on AI, but that's it. P ratio of 20. if the AI team reverts over the next few years. It doesn't need to happen next month, but I know Wall Street is focused on the next few quarters. So, P ratio of 20 going forward and I think that is again fairly priced for the situation. Another cyclical decline international paper, Smurf, Westrock, Packaging Corporation of America. I have squeezed them into the paper discussion here. Just as we do already cover one, we might cover them all. And then you can see what does cycle mean with international paper. I mean we have had one, two, three, four, four in the last 10 years shortterm cycles. Whoever bought here and sold here made the double four times in the last 10 years. That's insane. However, there is also Smurfit, Packaging Corporation of America, the leader of everything. High returns on capital. Smurfit also in a limbo there. Packaging Corporation just rocking it out of the ballpark. Now, when it comes to international paper, if I look at the cash flows in a downturn, they don't make any money. If you look at numbers, those don't really look great. The question is always what will change the above. In the outlook, there is not much. They're trying to stabilize saving, deal with higher input costs, and that has pretty much been the story over the last 25 years. Revenues declining, free cash flow with the ups and downs, ups and then again down. The above is not really a great return on capital for shareholders. Not to mention if there is a recession, less demand for cordugated paper and then it looks even uglier. Smurfitit also same story there. When I look at the return on capital for these companies, yes, Packaging Corporation of America did great timely acquisitions, scaling, everything good. The others are trying to catch up, but that doesn't mean that there will be a return on capital above the cost of capital for these companies. And then even if a year goes by, two years, the cycle looks better, everybody invests to eat up the competition and then prices go down again. So I think just leave the whole sector to pension funds. I'll be looking at these paper companies a little bit globally. There's Europe, there's Asia, and then yes, you can play a little bit around on those pricings, on those temporary somebody builds a new plant, somebody sells something or something like that. But that's not really long-term compounding because long-term the tailwinds are there, the market is growing, demand everything, but that's not reflected in stock prices, which means it's a very difficult environment. Absolutely no modes, no modes, competition, lower margins, ugly situations. Bungeie, it has been around for a while, but it was always a little bit lower quality compared to ADM when it comes to processing food situations, takeovers, always at the expensive side of doing things and capital allocation. Not that ADM was great, but that means also when there is a downturn, this stock goes much lower. When there is an upturn, this stock booms on the upside. If we look at the outlook P ratio of just 10, they're paying a dividend. They're doing buybacks. Everything looks good. Using cash flow to drive shareholder value. We have buybacks. We have dividends. Now growth capex that's always a big question and uh a lot of these companies say it is growth but then it's just because they're phasing out something else and then it's not really remarkable. There is debt as they trade it for inventories but you still have to pay. Some companies show it differently. ADM I think it has much lower. Anyway, you can see here, yes, earnings per share can be much higher in very positive environments. Unlikely we see this and then we are much lower now improving a little bit going into nine. Now it looks like cheap at the cyclical downturn. But when I look at these businesses, I really want the bottoms and that is a 5% yield, not a 2 and a half% yield. We did buy ADM here. This will likely follow in that line, but 2.8 give it to me a little bit less expensive because these are essential businesses. We'll follow ADM. It's covered stock on my research platform. So, we'll keep doing that. Now, APA Corporation depends on oil. Very simple. They have their production. The stock boomed especially over the last year. Production cost is around 50. So it will depend on where oil goes. I didn't find any gems in the rough. So if oil prices go down, this will go down. If oil prices go up, this will go up. I will be looking at oil. When it goes back below 60 50, then we'll make a comprehensive analysis and touch on this again. Now you can play around with it but it's not something for me. General Mills looks cheap dividend 7% but is a declining situation new models new leadership always something new to try to revamp the company but sales growth are going down and when it comes to sales when sales are down 3% inflation is 4% that means that actually sales are down 7%. I don't care about them selling this or selling that. That has no point. So, at some point, somebody will take this over. But I think the trend with the food brands is pretty clear. Yes, you can make 50% at a takeover or something, but it can also get much uglier over time. Compounder hunt transportation services P ratio 30 forward. Yes. 22. But it worked great over the last 25 years. However, I'm always wary of this because of the volatility. Give it a proper recession and then go and check the situation if you want to own these for the long term. Utility 3% yield. This is where utilities are priced now. I preferred them 2000 when we were looking at them. 6 7% dividend yields. Now it's a little bit expensive. Best Buy. Good news, the stock booms. Bad news, the stock crashes. It's insane. Maybe it was some value. If you want to bet on these retail things, now they are growing. Everything looks great. Stock is going up on expectations. But if there are bad news, you know what happens. Skyworks too complex for me. Not my cup of tea. We'll see how the merger goes there. read fairly priced in relation to interest rates we have discussed that Equifax mortgage market again housing stocks have been clobbered and that's simply how it goes Nordson compounding company technology solutions another AI growth business so they are benefiting from that booming but on free good quarters has been stable for a while declining and now booming. Good luck with that. Too much expectations. Another industrial P ratio 30. I'm not paying 30 times that. Dupont again bad cycle good cycle taking advantage of what's going on with Iran might last but over the long term you see it's hard to have this competitive long-term advantages. Bad situations. Good. Bad. Good. Now, good. Sluggish consumer. We'll see. Not cheap for the risk despite the decline. It might go everything with like Best Buys, things like that. CF now enjoying a good period in time. Let's look at it when it is ugly in the fertilizer sector. Another industrial priced in line with others. Insurance. I'm not a specialist on insurance. There is a discount. If you buy this, you get this and the rest for free. But that's how insurance usually trades. P ratio of 12 is standard. There are these cycles in insurance that are there and you have to accept them and then go look into when it looks ugly. But that's not my focus. We discussed genuine parts. I'll put the GPC and Mosaic links in the description below.
Commentaires 0
Connectez-vous pour rejoindre la discussion.
Se connecterAucun commentaire pour l'instant. Soyez le premier à partager votre avis !