…n, if you look at the acreage, the values there, we are practically trading now at the value of the land, the risks, dividend cut probably there is some debt. They can always sell land to cover the debt. So not like inherently risks there. But if you want to own this, now is this time to start buying. Be ready to buy more in stages and then trade around what happens with the cycle. In the meantime, the trees are growing. It's not stellar growth. What is it? The E number 2 something. That's the value of the trees that they are growing. They will be cutting less. More trees growing more value in the future. More boring…
But if you want to own this, now is this time to start buying. Be ready to buy more in stages and then trade around what happens with the cycle.
Contexte extrait par IA
If you look at the situation, if you look at the acreage, the values there, we are practically trading now at the value of the land, the risks, dividend cut probably there is some debt. They can always sell land to cover the debt. So not like inherently risks there. But if you want to own this, now is this time to start buying. Be ready to buy more in stages and then trade around what happens with the cycle. In the meantime, the trees are growing.
Transcription Complète
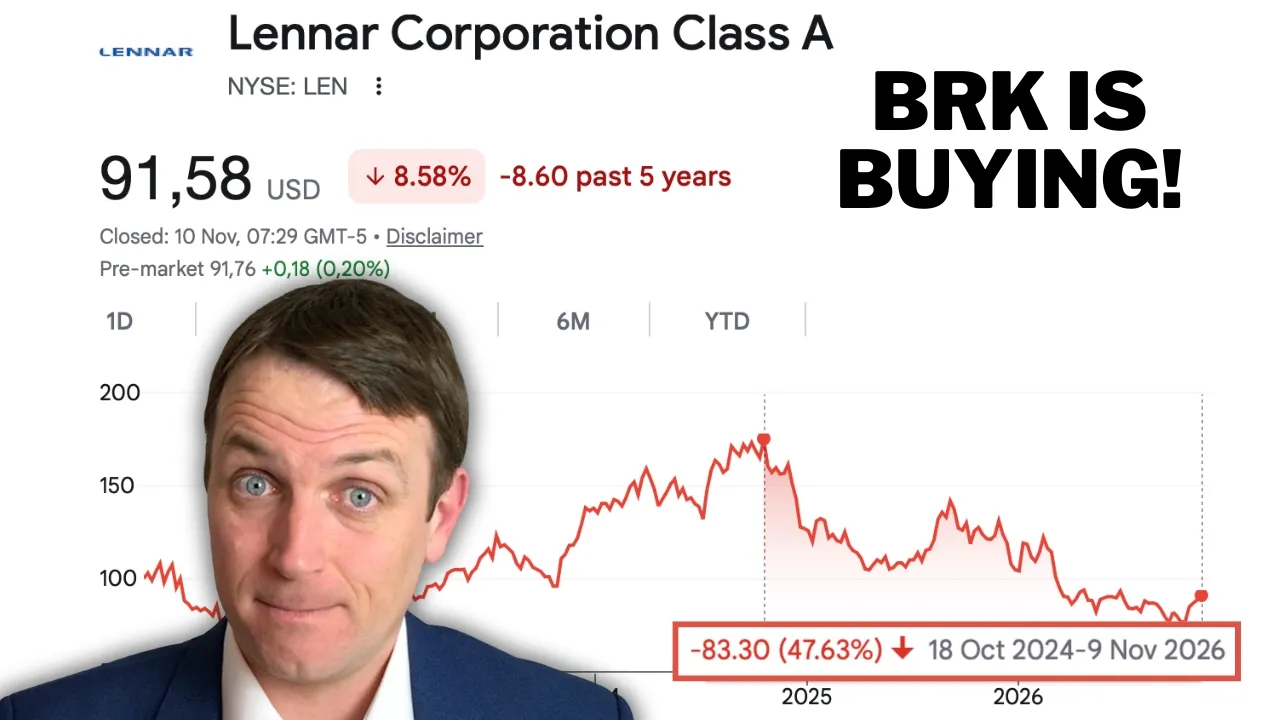
Good day fellow investors. We continue with our stock by stock analysis of the S&P 500 and today we're going to focus on homebuilders the housing sector with the three stocks that I highlighted warehouser lener and NVR. Then later I'll go through just giving my comment. I will not pursue all of these. There is another one Tyson Foods that's interesting perhaps to look after earnings next week. But housing as interest rates went up all these stocks are hit severely. So we have to see how that fits the environment. Let's immediately start with Leonard. So what has happened? Start of the year everyone was expecting interest rates to be lowered. That didn't happen. The reverse happened. Mortgage rates went up. Interest rates went up. Therefore, housing sales go down and that has hit the stock significantly. Lower earnings, lower revenues, more pressure there. They are selling with discounts to just keep the flow of houses going. Lower P ratio with the negative outlook. But but Buffett has been accumulating over time a little bit more increase the position. Not Buffett of course now anymore Birkshshire. And we have to see okay what's going on there? What kind of investment is it? Why is Buffett buying now in the great financial crisis all these homebuilders were buying the land owning the land that was a big drag on capital and when land prices crashed they had to impair a lot of value and many of those almost went bankrupt. They switched then to a light asset model. homebuilders where they don't own the land. They pay an option to hold the land to somebody else. As you can see here, they have lowered their land ownership and just controlled interests. The last part of that was spun out with Milro's properties that they practically still control, but it's not on their balance sheet anymore. The stock also up and down depending on the situation. There was a short report that recently pushed it lower. The dividend is very interesting at 12%. Some buybacks still on top of that which makes the situation very crazy. It's trading below book value very cheap. But what is this Milrose situation? First, it's controlled by Lener because the coco has 43% of votes and this is practically the company that owns the land and then it gets a fee for owning that land. So, if the land prices go up, the upside is kept because lener can just take okay, I'll take the land at that price. If land prices go down, the lenor company and other companies can just say no, I don't need that land, that's it. And they have to take all the losses. So these companies now are the loss, the bag holders in case of a next crisis. That's why the yield is 12%. If there is no crisis, no recession, no land prices going lower, this will give you 12% and also upside likely. If there is a crisis, these companies can go bankrupt and then the big boys will buy them on the cheap. But let's go back to Leonard Resiliency Asset Light. You can see here this risk where they impaired 89% of their equity is now comparable great financial crisis just 17% of equity. Nevertheless, that shift still didn't impact the market. Leonard is still trading at a discount to NVR that we'll discuss in a moment. That's the premium asset light founder inventor that everybody wants to be like. Earnings of course decreases everywhere. New orders decreased discounts deliveries okay but still profitable. So we have to now see okay earnings will not be eight but likely four going forward. And that is what Wall Street hates. But if we look at cyclical averages, let's say that over 10 years, let's say they make eight on average, 78. 78 compared to the stock price, that's a very low P ratio. That's a P ratio of 11. Compared to the market, if we go to 20 or when a rebound comes, that's a 2X. However, this is something I have very rarely or practically never seen. When it comes to investing, Leonard Corporation has a strong sell rating from Wall Street. When Wall Street says something is a buy, it's a hold. When it says it's a hold, it's a sell. When it says it's a sell, it's something terrible. And here we have 21 analysts from Wall Street. Everybody saying strong sell, sell, sell, and just one buy and one strong buy, which is actually a buy. The whole of Wall Street is against Leonard while Berkshire is buying. Of course, Wall Street is just looking. Housing is going down. Likely negative trend over the next year or something and therefore you should sell. Higher interest rates, higher mortgage rates make it less affordable to buy a house. But when EPS recovers to 10p ratio 15, the stock price is at 150 and you make your money and they make buybacks, pay dividends. So you get the dividend while you wait a little bit less likely buybacks, but Wall Street hates it. And what happens when Wall Street hates the stock starts to go up. It's not a bad way to play the cycle. Given cyclical allocation, it looks like a 10% return. That is why Burkshire is buying. So I have put it here at a little bit more risky given Wall Street something bad can happen in the next year or two. Put it on the quadrant. The quadrant video is just out. You can find the link in description below if you want update on other stocks. I think in the first part we covered this what I'm putting here and we will learn and watch over time. Very interesting if Birkshshire is buying you never know there is more protection even in case you of a crisis Bergkshire can overland some money give some money buy the whole company they have been buying stakes in these companies so that might be something very interesting let's go to NVR the asset light dream model everybody wants to be this company the stock is a 200 beggar over the last 30 years great numbers And here also new orders down. They are not changing prices. They are selling less. Keeping the margins. Earnings also down a little bit. But the company keeps on doing buybacks. You can see here the earnings are good and the buybacks are exploding. They spent a billion something in the last nine months compared to the market cap. That's crazy. Also something I haven't seen is that these guys spent already 17 billion in buybacks in history and that is now comparable to the market capitalization. If they spend another 17 billion in the next 10 15 years they will buy back the whole company at these prices. That's very interesting. Normalized midcycle EPS 500 P ratio of 12. Now on that midcycle average, if it goes back to 20, that's 10,000 compared to the current stock price of 6,000. So there is upside. It's not crazy upside. If housing still goes lower, this will go lower. When housing rebounds, this will go higher. Wall Street gives you the ratings and they tell you when it goes down, we will say sell. When it goes up, we will say buy. You just have to do the opposite in life. So nothing wrong high quality as always doing buybacks good buyback yield and you can bet with this one you can bet with lener depending on what you like when it comes to these it's not like you put all your portfolio you have to stage this okay I'm buying something now then if it goes lower in a recession 40% 40% down you buy more sell when it goes one leg up and then more impossible to know what the situation with housing will be. And let's go to the third one related to the sector. We have discussed it in a video 6 months ago. And here it is about owning timber, lumber, processing, land, a lot of acreage, just the land is worth the market capitalization. And then you have to see okay dividend will likely be lower as there are some pressures on the results. lumber always be turning into losses. The less rest is holding but this will just be seen later as now we have seen a decline in the housing less orders. This means this will translate into lower numbers next year for this company because those are the starting companies and then it with the lag will transfer into lower still lower demand and that's why you see the pressure on the stock. The outlook is still okay. Everything still looks there but we have to see how will this look let's say next year but a lot of that is already priced in. This was almost 40 bucks 5 years ago. Now it's 21. If you look at the situation, if you look at the acreage, the values there, we are practically trading now at the value of the land, the risks, dividend cut probably there is some debt. They can always sell land to cover the debt. So not like inherently risks there. But if you want to own this, now is this time to start buying. Be ready to buy more in stages and then trade around what happens with the cycle. In the meantime, the trees are growing. It's not stellar growth. What is it? The E number 2 something. That's the value of the trees that they are growing. They will be cutting less. More trees growing more value in the future. More boring than this it doesn't get. and you see how it has to fit your portfolio. Berkshire is buying lener not this and I think that is because Berkshire likes more growth housing in is in a crisis there will be more demand just survive the cycle so let's just finish with the rest of the stocks with a little bit of comment there Stanley Black & Decker has been destroyed over the last five years but now we are there P ratio of 20 I looked a little bit at the results yes If it returns to the cyclical normality but the competition is high 2022 was exuberance you have no mode things normalized maybe if margins normalize to historical levels you can see now margins are lower then it should improve earnings go up but P ratio still here high teens that's not that great for industrial like this fairly ly priced. I'm looking at the cash flows. That's that five, six, not to say six, seven% priced already good companies priced at a fair return. That's not that attractive. Nothing bad, but not really going to make you rich. Mid-American apartments, REITs. With REITs, you have the yield interest rates went up, dividend yields required went up, and the stock prices on these REITs went down. Each REIT is different. They have returned 8% per year for 42 years. Not bad, not stellar, but this you is what you can expect with these REITs. By the way, if you want to read, this will be open for reading on my stock market research platform. We'll put the link in description also of the video. Masco, another fairly priced in this market, has done greatly over time. Now, it's a little bit lower again related to housing. If valuation reverses, this then trades at a P ratio of 11. Same story there. I'm not that familiar with the company. They are devesting something but you can see the decline perhaps not that protected there in case of a recession. This is just too much tech for me. Anything can happen. ARR the fancy words now with AI and tech. No idea. Not my circle of competence. Ralph Lauren. Okay. Did great. CEO changed the company made it leaner. Increased prices. All really booming over the last year. Now it seems expensive because you never know with fashion. We did a lot of fashion companies, Lululemons, you are in fashion and then two years later you are not and then the stock looks extremely ugly. But it's very interesting how did they grow brand elevation, pricing power, direct to consumer, higher margins one over the Gen Z compared to others luxury that are suffering but too risky at these levels. another REIT 4.3% yield that's what the market is telling you about the REIT and with these REITs you simply you get what you pay a AI cloud computing anything can happen there looking a little bit what's going on not my cup of tea another REIT Kimco fairly priced in REIT land depending on what you need for your portfolio I'm not going to spend my time whether discussing whether REIT is priced at six or 4% not much gain for me there. Tyson Foods cyclical beef issues, beef pricing issues, chicken doing well, higher margins there. And here you can play a little bit with the cycle there if you want to own it. 3% dividend guidance update decline in guidance, but it is a dividend payer. They have first guided to good cash flows 1.2 to 1.7. Now it will likely be one to 1.2 and then we'll see how it trickles down into next year. But with that free cash flow at let's say 1.5 billion on average. This is trading at the P ratio or price to free cash flow 12 to 15. at the bottom of the cycle. You can see here their free cash flow historically looks positive. Remind me after earnings. I'll check the earnings and then maybe make a video. If it's not interesting, I will not make a video. Perhaps it needs to go much lower because the cycles there they are diversified a little bit. Okay. Depending on chicken, beef, disc inputs, outputs. But to buy this from a cyclical perspective, you need the trifecta. All those three segments to be bad. Then the stock will be very cheap and then you can really play with the margin of safety on the rebound. We discussed lion delasel here somewhere. It was ugly then and then we had Iran. It boomed back thanks to that. However, now it suffers because first Iran war pushed the plastic and all whatever they are doing prices higher, but now their input costs are going higher and that's putting pressure on them. Too crazy for me to know where will it go. Even if likely it will be a positive for the market, but for them as the production there in Iran has been destroyed, less competition, higher prices, but you never know, recessions and things like that. Fair Isaac, we discussed it. Nobody knows where it will go. Ball your aluminum cans for the beers and colas fairly priced. P ratio forward is 16 something like that. So as long as it goes, it is okay. They are buying back shares. Uh they are operating leverage some volume growth and their target is to grow earnings 10%. As long as it goes like that, everything is well. If there are some shocks, then a lot is lost, which is always the risk with these kinds of businesses. Hotels, everybody likes hotels. 3% yield, 7% growth, 10% return. The 7% yield, 2% growth. That's where the REITs are priced for the risks. CH Robinson compounder AI taking over the company and then they make an acquisition and the market doesn't really like it. No recession discussed ever. So that is the topic here for the conclusion. I don't do insurance. I don't do bo. I don't do pharma. So that's why I skip some. But housing is very interesting here. For the rest I'm going to say the word recession. You don't hear that word a lot. But a recession is not priced into any of these industrials, S&P 500, good companies, good brands, nothing wrong with the businesses. But if there is a recession, the whole of the SAP will be hit hard, not just the AI. I'm doing one of these videos per week. You can subscribe for more. Check what I do on my research platform, my latest book, if you're into reading about value investing and the strategies there.
Commentaires 0
Connectez-vous pour rejoindre la discussion.
Se connecterAucun commentaire pour l'instant. Soyez le premier à partager votre avis !